If you're trying to buy a home , affordability is probably what keeps you up at
night. And as you watch mortgage rates tick up again lately, it’s fair to wonder if
you should just hit pause and wait for them to go down.
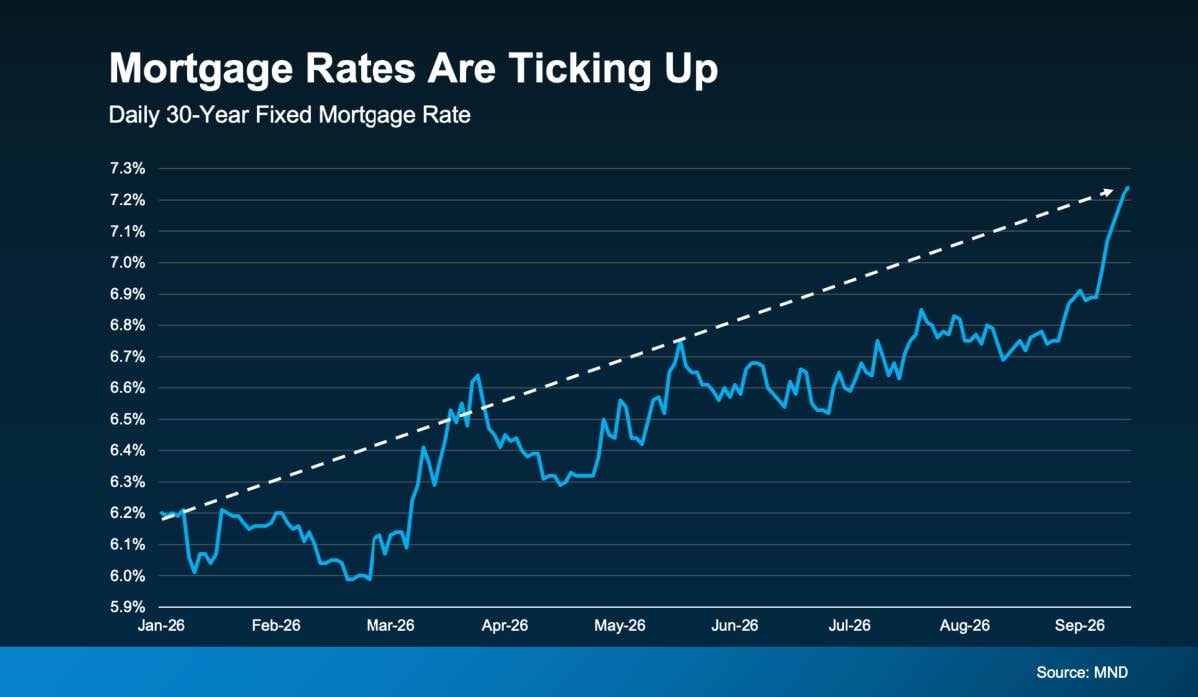
For now, though, they’re headed the other way. Mortgage News Daily data shows
how rates have risen this year ( see graph below ):
And if you’re wondering why? There are actually a number of reasons.
Mortgage rates are impacted by the situation overseas, economic data, inflation
numbers, oil prices, and even decisions from the Federal Reserve (who recently
decided to hike their Fed Funds Rate – which often affects mortgage rates too).
As Danielle Hale, Chief Economist at Realtor.com , explains:
“The pressure on mortgage rates was here even before the Fed rate hike, and it
doesn’t show signs of relenting. . .”
Now, that’s probably not what you wanted to hear. But, it doesn’t mean there’s
nothing you can do. While you can't control where rates go from here, you
absolutely can control several things that shape the rate you actually get.
So where should you focus? Let's walk through it.
Work on Your Credit Score
Your credit score plays a big role in the rate you qualify for, and even a small
improvement can make a real difference in your monthly payment. As Freddie
Mac puts it : "Generally, the higher your credit score the more options will be
available to you, including better loan terms and a lower interest rate."
So, make sure you do what you can to keep your credit score up. If you're not
sure where your score stands right now, or how to improve it, talk to a trusted
loan officer.
Explore Your Loan Options
The type and term of your loan both affect your rate. Conventional, FHA, VA, and
USDA loans each come with their own requirements and rates, and your term
(15, 20, or 30 years) changes both your payment and the total interest you'll pay.
The structure matters, too. A fixed-rate loan holds the same rate over time, while
an adjustable-rate loan usually starts lower and can move later on. Bankrate
explains it this way:
". . . rates on fixed-rate loans are typically higher than introductory rates on
adjustable-rate loans because the fixed-rate lender takes on the risk that rates
could increase during the loan’s term. Likewise, government-backed FHA, VA
and USDA loans sometimes have lower rates because they have a government
guarantee or insurance that cuts the lender’s risk."
It’s important to explore your options with a lender to see what makes the most
sense for you. Just be sure to balance your goals, your possible rate, and any
potential tradeoffs before making any decision. You may even want to talk to
multiple lenders to see how the options vary.
Consider a Newly Built Home
Another path to a lower rate comes down to the kind of home you buy. Many
builders are buying down mortgage rates, which lowers your monthly payment.
It’s just one way they’re trying to attract buyers and get their homes sold.
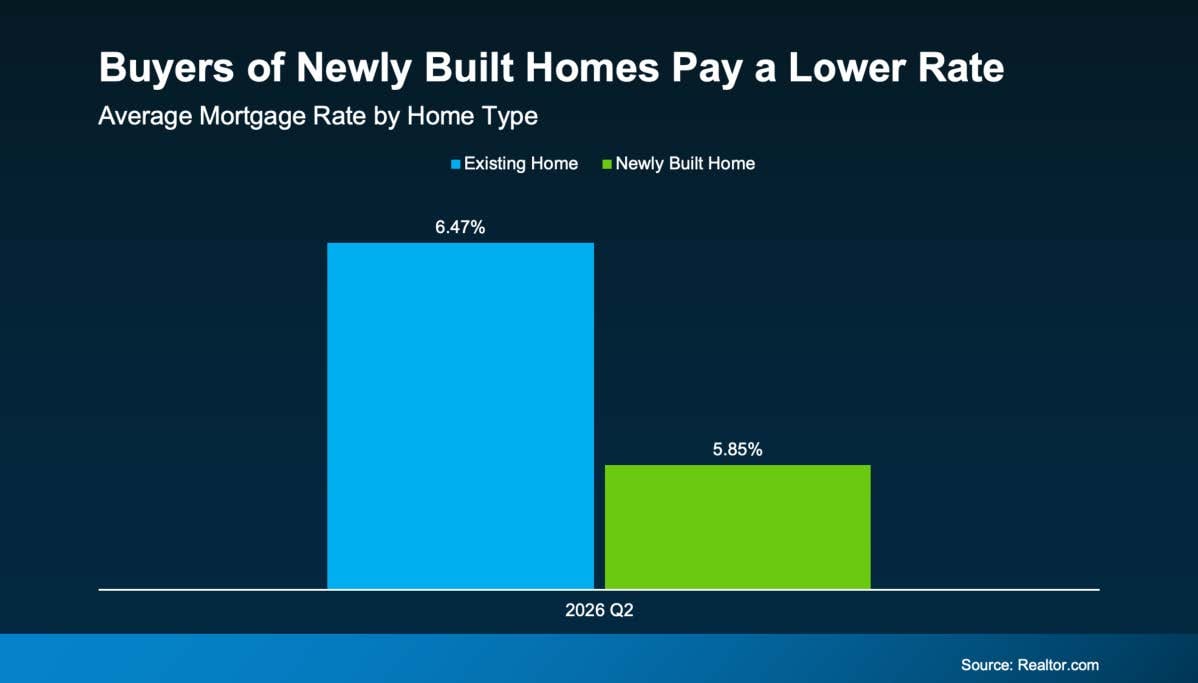
According to Realtor.com , buyers of newly built homes landed a lower average
rate last quarter than buyers of existing homes ( see graph below ):
If a lower rate is your goal, it may be worth asking your agent to show you some
new build communities that are offering this type of incentive locally.
Bottom Line
You can't control where mortgage rates go, but you can control your credit, your
loan, and the kind of home you buy. Working with a trusted lender can help you
lock in the best rate you qualify for. And when you’re ready to make a move that
fits your budget, let’s connect.